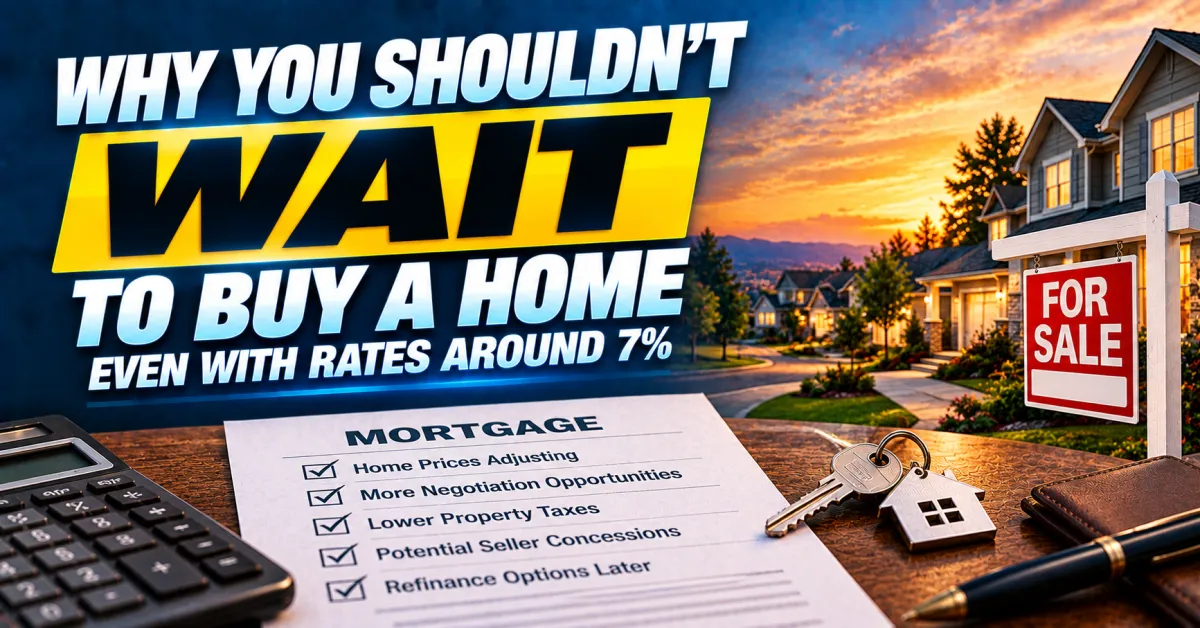
Why Waiting for Lower Rates Before Buying a Home May Cost You More Than You Think Right Now
The Case for Buying in Today's Market That Most People Have Not Heard
Rates are in the low sevens. Buyers are hesitating. And Nathan Rufty at Canopy Mortgage wants to walk through exactly why waiting may be costing buyers more than the rate they are waiting to avoid.
What Is Actually Happening in the Market Right Now
Sellers who have been on the market for thirty, sixty, or ninety days and beyond are adjusting. Price reductions are happening with real frequency as sellers reach the point where sitting is no longer a viable strategy. Some sellers cannot sustain the mortgage payment and must move the property. Thirty, sixty, and ninety day delinquencies are increasing. Short sales are beginning to appear.
For buyers this creates a specific and time-limited opportunity. The seller who has been on the market for ninety days is a fundamentally different negotiating partner than the seller who listed last week. The motivated seller is willing to have conversations about price, concessions, and terms that the fresh listing simply is not.
A Historical Perspective Worth Understanding
Nathan has been in the mortgage business since 1988. That perspective matters here because he can speak to what normal actually looks like across multiple decades and market cycles.
The rates that dropped to the ones, twos, and threes during the pandemic required a catastrophic global event to produce. That is not a policy outcome. It is not something the Federal Reserve achieves by adjusting the Fed funds rate. It is the result of emergency intervention that accompanied massive economic disruption. Expecting a return to those rates without a comparable disruption is not a realistic planning assumption.
For most of the years between the exotic lending era of 2002 to 2005 and the post-crisis normalization current rates are lower than what existed for significant stretches of time. The stated income programs and no-income-no-asset products that made that era's rates accessible to anyone who could fog a mirror no longer exist. Today's borrower needs to demonstrate income, credit, and assets. If those three factors are present the conversation about buying should be happening now.
The Property Tax and Insurance Factor Nobody Talks About
Here is the part of the buy-now argument that most people never hear. Homeowners insurance and property taxes are both tied to the purchase price of the home.
A buyer who purchases at a lower price point today locks in lower property taxes based on that purchase price. A buyer who waits and purchases later at a higher price point pays higher property taxes from day one and every year after. The same logic applies to homeowners insurance which is based on loan amount and replacement cost.
Every year of appreciation that happens while a buyer waits produces a higher property tax basis when they finally purchase. The monthly savings from a marginally lower rate can be partially or fully offset by the higher recurring costs that come with a higher purchase price.
How Nathan Approaches the Qualification Conversation
The framework he uses is built around what the buyer is comfortable paying each month rather than what the maximum qualification allows. Tell him the payment ceiling. Tell him the down payment available. He works backwards from those two numbers to identify the purchase price range, the property type considerations, and the loan program options that produce an outcome the buyer can actually live with comfortably.
From there the conversation with a realtor about offer structure, seller concessions, and rate buydowns becomes actionable rather than theoretical. A seller willing to contribute toward closing costs in the current buyer-favorable market can redirect those funds toward buying down the rate which reduces the payment in ways that make the numbers work even at current market rates.
What Happens When Rates Come Down
The fixed principal and interest payment on a mortgage does not go up after closing. That is the commitment the lender made and it holds regardless of what happens to rates after the loan closes. Property taxes and homeowners insurance adjust annually but the core payment is locked.
When rates do eventually improve the refinance option becomes available. A buyer who purchased at today's lower price with today's seller concessions negotiated into the deal can refinance into the improved rate without having paid the higher purchase price that a future competitive market may require. That sequence produces a better long-term outcome than waiting for the rate while the purchase price climbs.
Nathan Rufty is licensed in Arizona, California, Nevada, and Utah. He is not interested in pressure sales. He is interested in a conversation about what is actually possible for each buyer's specific financial situation right now and what steps a buyer who is not yet ready needs to take to get there.
Call 909-503-5600 to start that conversation.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
NAR.realtor
Investopedia.com